From 1 October 2025, the Australian Government’s 5 percent Deposit Scheme removed place limits and income caps while raising property price caps, allowing more first‑home buyers to enter the market with as little as a five percent deposit.
These changes mean it’s easier to get into the property market – but they don’t remove the need for a cash deposit or genuine savings when you exchange contracts. Deposit bonds still fill an important gap, especially for auctions and off‑the‑plan purchases.
Keep reading for:
- How the 5 percent deposit scheme has expanded and what it means for Sydney buyers
- Deposit bonds in 60 seconds: what they are and how they work
- When deposit bonds still win – private treaty, off‑the‑plan and bridging
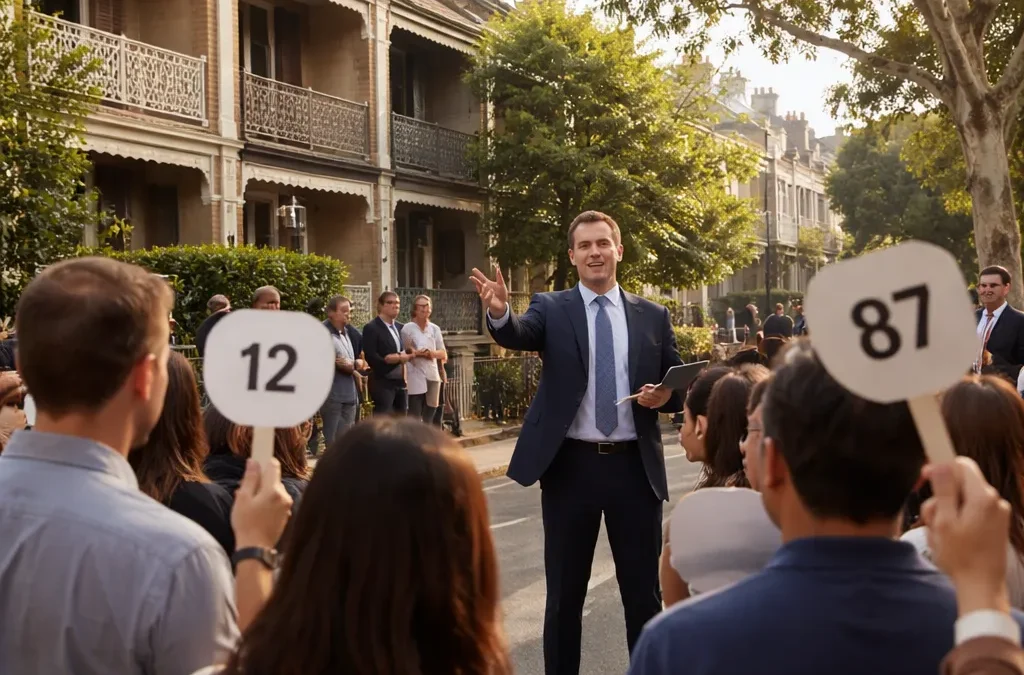
- Why auctions are different and how to talk to the agent about acceptance
- A quick script for telling the vendor you’re using a deposit bond
Quick answer
- The expanded 5 percent scheme removes place and income caps but still requires a cash deposit at exchange.
- A deposit bond is a guarantee backed by an insurer that covers 5–10 percent of the purchase price until settlement.
- Deposit bonds can be accepted for private treaty sales, off‑the‑plan purchases and long settlements, but they’re rarely accepted at auctions.
- If you’re using a deposit bond, you still need to show lenders how you’ll fund the full deposit and meet serviceability rules.
- Always confirm with the agent and vendor whether a deposit bond is acceptable before you sign or bid.
Why do the 2026 deposit changes matter in Sydney?
The 5 percent Deposit Scheme now offers unlimited places, no income caps and higher price thresholds – in NSW’s capital this means price caps have jumped to $1.5 million, opening doors for more buyers.
- Unlimited places: any eligible buyer with a 5 percent deposit can apply (Home Guarantee Scheme)
- Income caps removed, making the scheme accessible to higher‑income households
- Property price cap in Sydney increased to $1.5 million to reflect market values
- Regional guarantees rolled into the main scheme for simplicity
These changes mean more competition at auctions and private sales, but they don’t eliminate the need for funds to complete your purchase.
If you’re unsure how the scheme works for your situation, explore our first home buyer support or contact us for guidance.
What is a deposit bond and how does it work?
A deposit bond is a guarantee issued by an insurer that replaces the need to pay a cash deposit at exchange. It’s not a loan – you still pay the full deposit at settlement.
- Covers between 5 percent and 10 percent of the purchase price
- Seller receives the deposit in cash at settlement, not at exchange
- Issued for a specific property, amount and timeframe
- Requires a one‑off premium paid to the bond provider
Using a deposit bond can free up cash for other costs like stamp duty or renovations, but it doesn’t replace the need to demonstrate genuine savings.
Learn more about deposit bonds and how they fit within your finance strategy by visiting the Moneysmart home loans guide.
When do deposit bonds still win – and when don’t they?
Deposit bonds shine in situations where timing is flexible, but they have limits during competitive auctions.
- Accepted for private treaty sales and off‑the‑plan contracts when the vendor doesn’t need immediate cash
- Useful when you’re buying and selling simultaneously and funds are tied up in your existing property
- Not usually accepted at auctions because contracts are unconditional and sellers want cash immediately
- Often rejected when multiple buyers are competing or when the seller needs funds for their own purchase
Always ask the agent whether the vendor will accept a deposit bond before relying on one, especially if you plan to bid at auction. For official auction rules, see the NSW Fair Trading auction guidance.
For a deeper discussion of when deposit bonds work best, speak to our team about your deposit options.
How do you talk to an agent or vendor about deposit bond acceptance?
Clear communication builds confidence – outline that the bond is legally enforceable and backed by a recognised insurer.
- Explain that the bond guarantees payment of the full deposit at settlement
- Confirm the bond issuer’s credentials and provide the certificate in writing
- Discuss timing – make sure the bond expiry aligns with settlement
- Ask the agent to check with the vendor’s solicitor so everyone is on the same page
A short script can help: ‘We’re using a deposit bond issued by a major insurer. The bond covers the full deposit and will be paid at settlement. Here’s the certificate. Can you confirm the vendor is comfortable with this arrangement?’
If you need help preparing a script or understanding the legal aspects, our team can assist.
Quick reality check
Deposit bonds don’t eliminate the need for a cash deposit – lenders still assess your savings and serviceability.
Not all vendors or auctions will accept a bond; acceptance is always at the seller’s discretion.
The bond fee is non‑refundable, so you’ll lose it if the purchase doesn’t proceed.
Even with the 5 percent scheme, lenders will stress‑test your loan using a 3 percent serviceability buffer and may limit debt‑to‑income ratios.
Check eligibility and seek advice before committing to any deposit strategy.
| Scenario | Best deposit option | Watch‑outs |
| Auction with unconditional contract | Cash deposit | Deposit bonds rarely accepted; funds must be available immediately |
| Private treaty sale | Deposit bond or cash | Confirm seller’s acceptance and bond expiry aligns with settlement |
| Off‑the‑plan purchase | Deposit bond | Ensure long bond term and factor in non‑refundable fee |
| Buying before selling | Deposit bond | Only works if your sale is secure and settlement dates align |
Deposit bonds remain a useful tool for Sydney buyers navigating the expanded 5 percent scheme. They provide flexibility when cash is tied up, but they aren’t a silver bullet.
Always confirm acceptance, understand the fee structure and ensure you can meet lender serviceability requirements. A combination of genuine savings and a deposit bond often delivers the best outcome. To learn about our experience, see our About page.
Ready to explore deposit bonds or other deposit strategies? Contact our team for calm, tailored guidance.